

S&P 500 futures and Nasdaq 100 futures are trading higher ahead of the open, with strong results from SpaceX and Super Micro Computer revitalizing the AI trade.
The benchmark US stock index gained on Tuesday as crude oil tumbled amid an unconfirmed (and later denied) report that the US and Iran are close to reaching a deal to end the war.
The S&P 500’s advance-decline line cleared 300 for the first time since April 8 — the session after President Donald Trump announced an initial ceasefire.

A skeptic might look at a potential SpaceX-Tesla merger and think that Elon Musk wants to consolidate his empire in order to have a single outlet to be the object of his cult following’s affection, rather than divided investor attention between one favored progeny and another red-headed stepchild.
Quite frankly, that was my presumption. But looking at dollar volume traded or options activity, there’s not too much evidence to suggest any idiosyncratic cannibalization of interest in Tesla following the SpaceX IPO.
Yes, SpaceX was the most-bought stock by Robinhood traders ahead of earnings on Tuesday, and Tesla the second-most sold. But this was the exception that proves the rule: the two have typically seen net purchases behavior move in tandem, and both stocks have enjoyed steady accumulation since mid-June (admittedly, with SpaceX’s being much hotter).

Overall, traded value in Tesla has moderated significantly — but that’s true for the market as a whole too, rather than a company-specific phenomenon.

Call volumes are also off the boil, but the same trend in Tesla is also visible in Nvidia. This seems to have more to do with the breakdown in the AI momentum trade than any acute loss of options-based appetite in one single name.

Anywho, it’s fun to muse about a SpaceX-Tesla tie up, but the real story is that SpaceX has already been reverse taken over by xAI, with the super intelligence business’ results largely responsible for the company’s surprisingly strong showing in Q3.
AI revenue of $7.56 billion made up more than half of SpaceX’s sales for the quarter, exceeding both the space and connectivity units. That figure not only crushed the $6.3 billion consensus estimate, but bested the projections of all 22 analysts polled by Bloomberg, and the segment’s adjusted EBITDA of $4.95 billion likewise exceeded every bean counter’s expectation.
“So talking about SpaceX Super Intelligence, SpaceX SI, sexy, whatever…” -Elon Musk on SpaceX’s Q3 earnings call
As a subsidiary of Robinhood, Sherwood Media is restricted from writing about any company in which Robinhood is or was a selling group member of the IPO during the regulatory "quiet period" for that company.
“Scale-then-Monetize”
Meta has provided an interesting example of what excites investors about the AI boom, and where they’re still skeptical.
The stock ramped to a 52-week high amid popular acclaim (and surging downloads) for Muse, fell from grace after its formal entry into the cloud/enterprise space, jumped again after the release of a new model, and then tumbled amid the reemergence of credit concerns that have bedeviled the AI trade at large.
TL;DR: Investors like novelty and new AI applications, and do not like a late entrance into a competitive marketplace. The more pessimistic alternative would be investors like anything new for a while — until they’re forced to think about the ROI.

Wall Street is looking for sales of $63.3 billion in Q3 with earnings per share of $3.85 when the social media giant reports results after the close on Wednesday, anticipating revenue guidance for Q4 to come in around $73.6 billion. The options market is pricing a move of roughly +/- 6.6% on these quarterly results.
But for a market seemingly obsessed with things like cash burn and CDS, recent focus on Meta has somehow shifted away from things like AI monetization and returns and toward metrics more commonly used to judge early-stage growth companies rather than bona fide tech behemoths.
That, of course, is thanks to Muse.
“Given Meta’s likely ‘scale-then-monetize’ approach, we suspect the stock likely continues to trade on Muse downloads, users, engagement, and retention in the near term, in addition to new model launches, which to date have put Meta back in the frontier discussion,” writes Deutsche Bank analyst Benjamin Black. “Bigger picture, we think we are likely at the start of a rich product cycle that will foreshadow the potential returns to the significant infrastructure and R&D investment Meta has made from AI agents / Enterprise / Advertising.”
However, Morgan Stanley analyst Brian Nowak flagged that while Muse gets a ton of downloads, it doesn’t get as much repeat traffic.

(As an aside, nobody seems to have told “consumer inertia” stocks about Muse’s retention issues!)

Higher retention would lead to a different challenge for Meta, according to Nowak.
“With current models, scaling any agentic product to hundreds of millions of users would likely require material capacity…speaking to how the agentic adoption path is likely going to be long...and require more efficient models (and improving model cost to serve),” he writes. “Consider that at ~10,000 tokens/second/GPU, 500 million daily users consuming 50 million tokens per week (50% of Muse’s free allocation) would require ~13 GW ...or ~100% of the total new compute capacity coming on at META in '27/'28.”
As we discussed on Monday, neither equity nor credit investors are offering a meaningful check on hyperscalers’ spending plans. The core businesses are doing well (with difficult-to-quantify boosts thanks to AI) and new applications like Muse offer future revenue streams to dream on.
The boom continues apace despite new models and fresh functionalities quickly becoming commoditized and capacity-constrained. In fact, the boom continues apace because new models and fresh functionalities quickly become commoditized and capacity-constrained!
So for the state of the AI trade, all that remains to be seen is whether this quarter’s edition of bigger revenues and capex budgets assuage nascent fears about the weaker cash-burning and leveraged parts of the ecosystem.
Gross Domestic Posting
I’m more than a little late but might as well give my two cents on this:

It strains credulity that AI maxis can ignore their lived experience this much!
If you work at a frontier lab, you should be intimately familiar with how supply shortages have impeded the quest for Digital God and the proliferation of its beta versions.
It is also beggars belief that employees in an industry seeing more and more financing constraints can remain blissfully ignorant of the existence of the Federal Reserve and the implications of the inflation-control portion of the central bank’s mandate.
The call on resources needed to approach growth anywhere near that pace would be massively inflationary. The Federal Reserve would act to counter that impulse with interest rate hikes that impede the boom, preventing said prophesied blockbuster growth from occurring.
Even the digital realm has to obey the speed limits imposed by material and financial realities.
SEE ALSO: Reuters reports that Anthropic “spent nearly $9 billion on computing capacity and infrastructure in the first half, up from $2.3 billion a year earlier, the S-1 document showed.”
Whispers from Wall Street
From BTIG chief market technician Jonathan Krinsky:
“We find ourselves in an interesting spot in that our conviction that the semi/AI complex is making a meaningful top has increased over the last few weeks, yet the risk/reward for a tactical bounce has also become quite favorable. Equal-weight semis (XSD) have pulled back and thus far held the 200 DMA while SOXX is showing downside exhaustion and nearing its own 200 DMA. If semis can't bounce here, then when can they? In other words, we have a strong view that a tactical bounce in semis should materialize in the coming days, but if they can't, we aren't going to defend them when our big-picture view remains cautious, with our conviction only growing.”

Seen on Socials
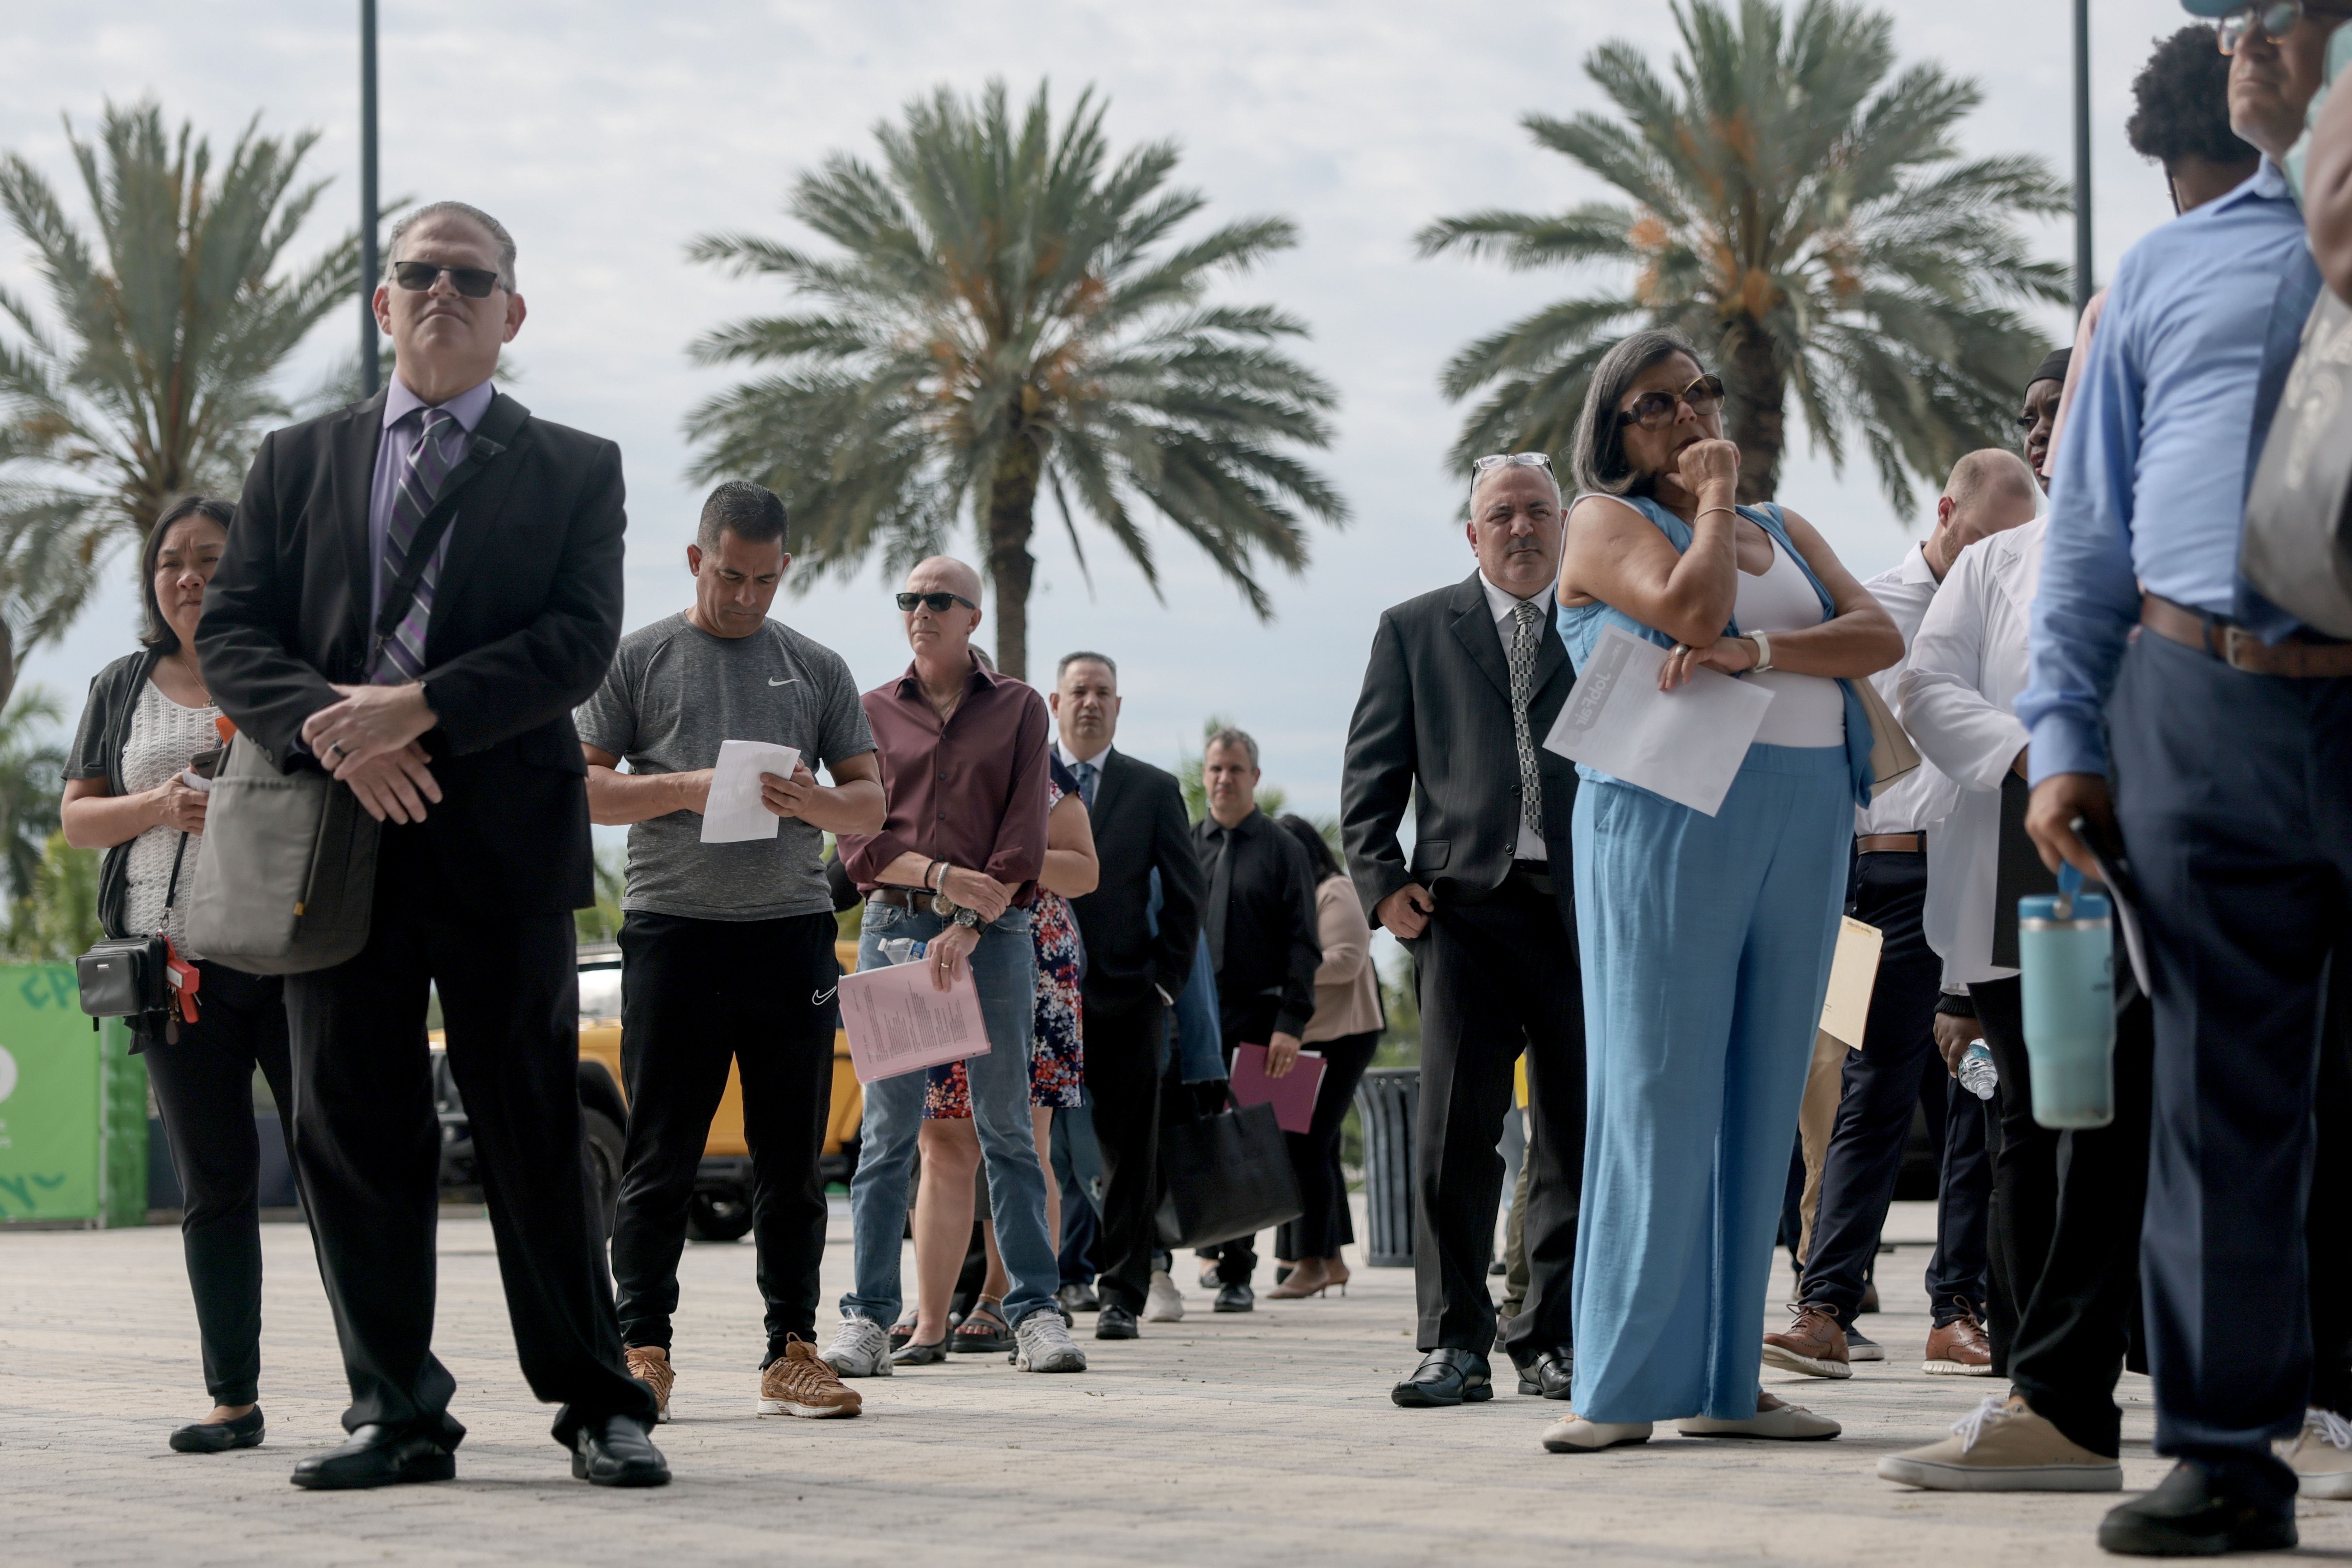
Via Ara Kharazian on X:

What to watch
Wednesday:
Meta, Tesla, IBM, Southwest Airlines, and Crown Castleresults due out after the close.
Thursday:
Lockheed Martin, TTM Technologies, and Procter & Gamble slated to release earnings ahead of the open.
Postmarket earnings due out from Western Digital, Bloom Energy, and Comfort Systems USA.